Main Street Agency Multiples: What Your Book Is Worth 2026
Main Street agency multiples in 2026 split sharply from the 11x headline. See what a small personal-lines book actually sells for and why the gap exists.
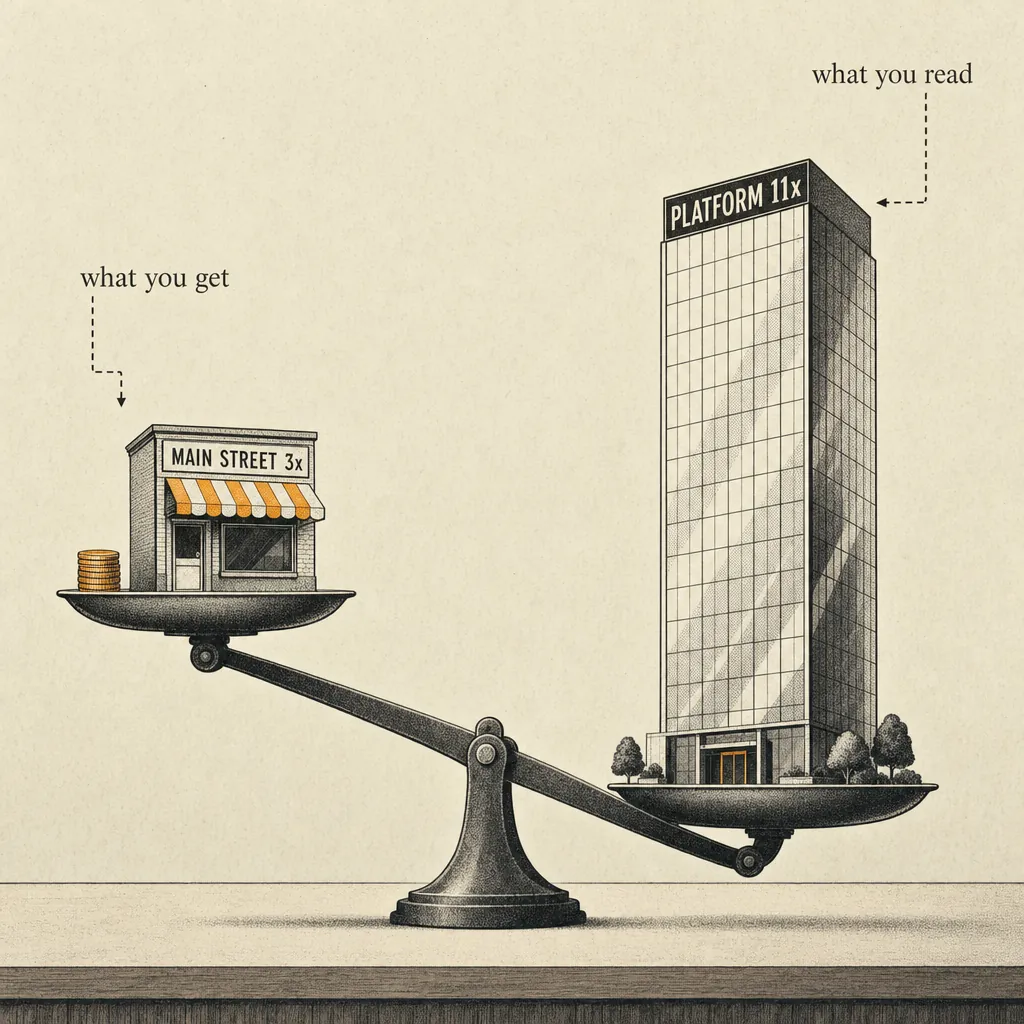
In 2026 a Main Street agency does not sell at the 11x EBITDA headline. Small agencies under about $2 million in earnings transact at roughly 3.0x to 3.8x seller discretionary earnings, and personal-lines books at 5x to 7x EBITDA, while platforms pay 11x and up. The gap is size, retention, and growth mix.
Key Takeaways
- Headline brokerage M&A averaged 11.50x upfront EBITDA, but that skews to $1 million plus EBITDA and platform buyers.
- Small agencies in the $500K to $2M earnings band transact at 3.0x to 3.8x earnings, not 11x.
- Personal-lines-heavy books trade at 5x to 7x EBITDA while specialty and benefits books reach 9x to 12x.
- Deal volume is down 40% off its five-year average, which puts pressure on rate-dependent sellers.
- Organic new-business growth, not rate increases, is the buyer signal holding premium pricing in 2026.
Why does the 11x headline misstate a Main Street exit?
The most-cited "average" number floating around 2026 is an upfront multiple of 11.50x EBITDA across all firms, rising to 15.48x if the full earnout pays out, per MarshBerry data. That is a real figure, but it describes an advised, larger transaction, not a small agency sell. MarshBerry itself is explicit that brokerages transact in a wide band "from the mid-single digits to the mid-teens," and that the firms earning above-average multiples are larger and more profitable.
The average is doing what averages do when one end of the sample is enormous. Platform-tier and mid-market deals pull the arithmetic up, while the long tail of small, owner-run agencies trades far below it. Sica Fletcher flagged this same widening gap in its 2026 commentary, describing an "unheard of" gap between the top and the rest of the broker market. The multiple you can actually command is set by the size band you sit in, not the industry average.
What does a small book actually sell for?
The number that matters for a Main Street exit is the size band you are in. Axia Growth's transaction dataset breaks it out directly: agencies in the $500K to $1M seller discretionary earnings range transacted at a median of 3.0x, with an interquartile range of 2.5x to 3.6x, and the $1M to $2M band moved to 3.8x. The multiple does not jump until you cross roughly $2M to $5M, at 6.8x, and $5M to $10M at 8.1x.
That gap between the sub-$2M band and everything above it is the entire Main Street reality in one table. Ad Astra Equity's benchmark page carries the same directional message: personal-lines P&C books trade at 5x to 7x EBITDA, commercial at 7x to 10x, and specialty or employee-benefits books at 9x to 12x. BizBuySell's average earnings multiple for small insurance agencies was only about 2.68x in the 2024 to 2025 window, below its own five-year average. That is the owner-run, personal-lines reality the platform headlines do not capture.
What widens or closes the multiple gap?
Four levers move a Main Street book inside this band, and most of them are within your control with 18 to 24 months of runway.
Book retention is the first and largest. A 90% plus retention book earns premium pricing and higher cash at close, while a sub-80% book triggers heavier earnouts and compresses the multiple by two to three turns, per Ad Astra's analysis. Buyers audit three-year premium-level retention, not a single good year, so a one-time blip needs documentation, not hope.
Line-of-business mix is the second lever. Personal-lines books trade at the bottom of the band because the renewal is more commoditized and attrition-prone. Specialty and employee-benefits books command 9x to 12x because the program expertise is harder to recreate organically. Moving even part of the revenue mix toward commercial or specialty shifts the multiple meaningfully without growing EBITDA.
The third is where your growth came from. OPTIS Partners managing partner Tim Cunningham was direct about 2026 pricing: agencies with producer-led organic growth and strong benefits or specialty books hold steady, while agencies whose growth came mainly from rate increases "will see lower multiples and larger earnouts," per the Q3 2026 OPTIS report. With commercial rates now falling rather than rising, a buyer can no longer credit top-line growth to a favorable rate cycle.
The fourth is concentration. A single producer driving more than 25% of revenue, or one carrier representing too much of the book, gets priced as retention risk and compresses the multiple, per Ad Astra's value-driver breakdown.
Why is 2026 a more selective buyer's market?
Deal flow is clearly down. OPTIS counted 292 U.S. and Canadian agency deals in the first half of 2026, the slowest start to a year since 2016 and down 15% year over year. Through September the count reached 439 announcements, a pace 40% below the previous five-year average, with the year-over-year decline at 27%. The buyers are also consolidating into fewer hands: 10 firms accounted for 45% of first-half deals, and private-equity-backed buyers took 76% of transactions, per OPTIS.
That does not mean the market is closed. OPTIS, MarshBerry, and Sica Fletcher all describe demand for quality agencies as still strong. What it means is that the marginal seller, the one whose value came from rate tailwinds instead of new-business production, is facing a tougher conversation than they would have two years ago. MarshBerry ties the valuation premium directly to organic growth that shows up over multiple years, not to a single hard market.
What is the operator's take on Main Street multiples?
The 11x headline and the 3x Main Street reality are not two markets, they are two ends of one market, and the one you land on is mostly a decision you make before you list. Retention above 90%, a book that is not 60% personal lines, and organic growth that does not depend on a hard market are all levers an owner can pull with an 18 to 24 month head start. The 2.68x small-agency average in the BizBuySell data is the price of selling the business as it is, not the business as it could be. The owner who runs the exit only when they are emotionally done gets the 3x end. The owner who spends two years building the book a platform wants to buy gets into the conversation where the 8x and higher multiples actually happen.
Frequently Asked Questions
What multiple do small insurance agencies sell for in 2026?
Small agencies under about $2 million in seller discretionary earnings transact at roughly 3.0x to 3.8x earnings, per Axia Growth's transaction data. A personal-lines-heavy book typically trades at 5x to 7x EBITDA depending on retention and mix.
Why is the industry average multiple so much higher than what I can get?
The 11.50x average is skewed by large, advised, platform-tier deals where private-equity buyers pay 11x and up for $1 million plus EBITDA firms. Your multiple is set by your size band, retention, and line-of-business mix, not the industry average.
Does slower M&A volume in 2026 hurt my exit?
Deal counts were down 40% off the five-year average through September 2026, but demand for quality agencies held steady. The pressure falls on rate-dependent sellers; agencies with organic new-business growth and strong books still command premium pricing.
What should I do before selling to get a better multiple?
Drive retention above 90%, shift mix toward commercial or specialty lines, build organic growth that is not rate-dependent, and reduce producer and carrier concentration. Ad Astra and MarshBerry both describe these as the levers that separate the 3x to 5x band from the 8x and above band.
Sources
- Insurance M&A Pace Down 15% in First Half 2026: OPTIS
- Insurance Agencies M&A: Buyers & Multiples (2026), Axia Growth
- Insurance Agency Valuation & EBITDA Multiples, Ad Astra Equity
- Insurance Broker Valuations: What Is The Right Multiple, Sica Fletcher
- How To Think About Value, MarshBerry
- Insurance Agency M&A Down 40% in 2026, Agency Checklists
Related Reading
Calculate Your Agency Value
Get Started →Written by licensed property and casualty agency operators on the Insurance Dudes M&A Desk. Insurance Agency Trader is US-based, serving independent and captive agency owners across the United States.
Editorial process: every post is reviewed against our published valuation math and current market data before it ships, and updated when the numbers move. Corrections: email craig@insuranceagencytrader.com and we will fix errors promptly.